Europe’s sugar balance sheet may be missing a large volume of sugar. Sugar imported under Inward Processing (IP) is not counted in EU sugar stocks, because it enters in bond and should be re-exported in processed products within a year. In the first ten months of the marketing year, 883,000 tonnes of IP sugar entered the EU while only 171,000 tonnes left. That follows an IP surplus of 476,000 tonnes the year before. Taken together, EU stocks could be at least 500,000 tonnes higher than the market has been led to believe.
IP imports grew after the 2023 price spike, and the trade was later suspended under pressure from growers, processors and the ACP group. The main raw sugar refiners on the Iberian Peninsula have since filed lawsuits against the Commission.
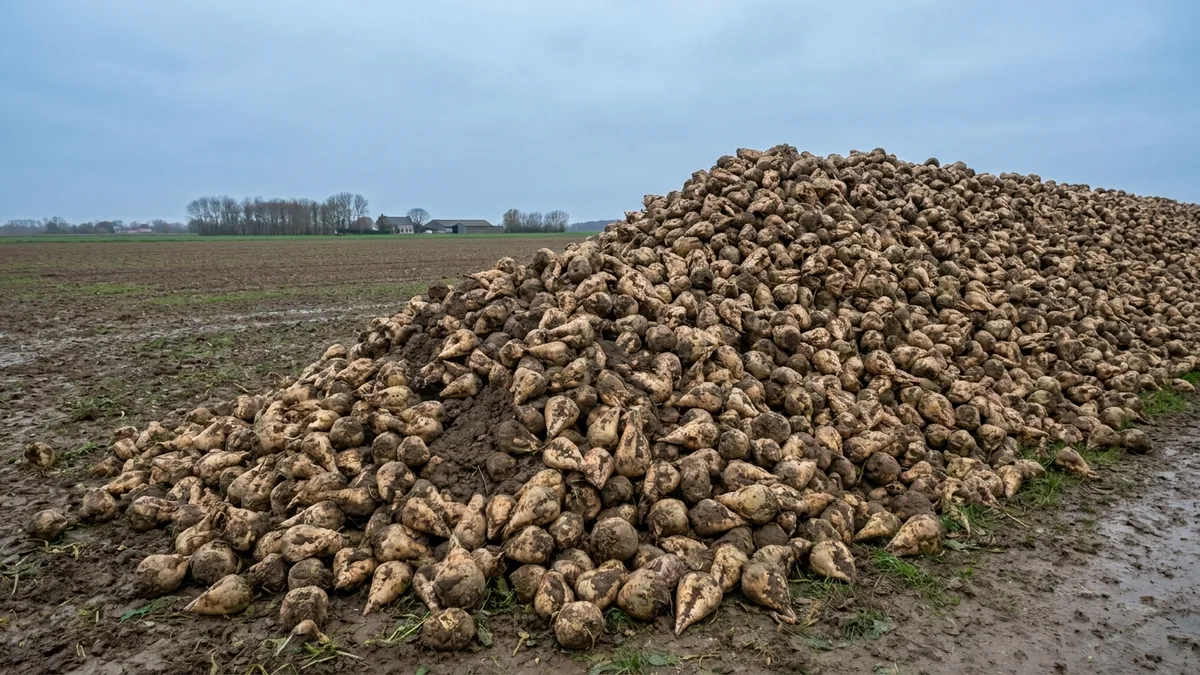
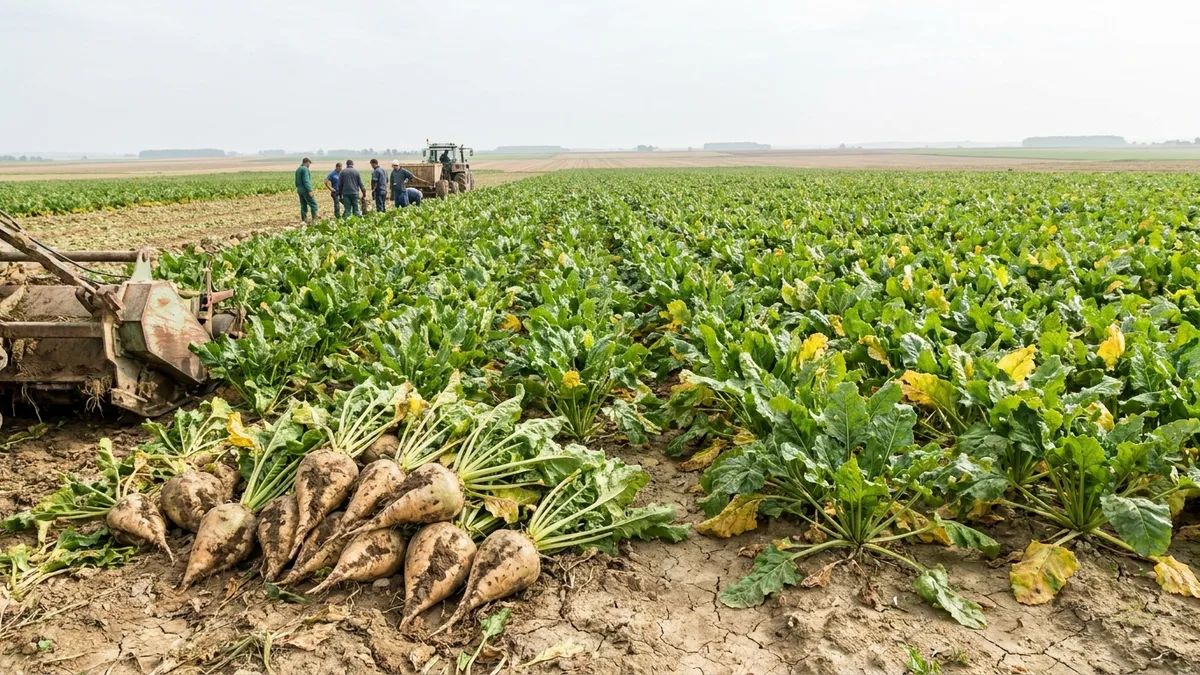
Meanwhile, the crop keeps disappointing. French beet yields are down more than 25% on last season, and disease is slowing slicing: Tereos is running with only two days of beet in its silos for fear of Rhizopus spreading to healthy beet. Dutch sugar content is stuck at 15.9°, and Cosun has told growers the profit bonus will be very low or possibly zero. Poland’s government forecasts sugar production about 20% below 2025, although our analyst expects the final drop to be closer to 10%.
Most of the crop is already priced. Between 70% and 75% of expected production is believed to have been sold, and our analyst sees the EU sugar industry facing probably its hardest period since 1975.
Read the full European sugar market analysis here.